The Financial
Marketplace
is Evolving Rapidly.
As digital financial services continue to reshape the industry, credit unions need flexibility to adapt and better serve their members. Credit unions need choice now more than ever.
For more than 50 years, American Share Insurance (ASI) has provided that choice as a credit union-owned share guaranty corporation protecting more than 1.44 million credit union members. Since 1974, no member has ever lost money in an ASI-insured deposit account.
Today, ASI advocates for the right of credit unions to choose private deposit insurance while expanding excess insurance for both federal and state-chartered credit unions. Through policy, education, research, and engagement, we’re working to preserve a strong, competitive insurance marketplace and strengthen options for credit unions.
One Mission.
Greater Protection.
Excess Share Insurance (ESI), a wholly owned subsidiary of American Share Insurance, provides supplemental deposit insurance to privately and federally insured credit unions nationwide ESI was built on the strength of ASI and the private insurance system it pioneered. Supporting private insurance helps preserve innovation, strengthen state charters, and ensure credit unions continue to benefit from competitive insurance solutions.
Our Advocacy
Priorities
Federal
Regulatory Parity
Credit unions deserve a level playing field. ASI advocates for federal policies that ensure privately insured credit unions receive equitable regulatory treatment and equal access to federal programs. By removing outdated statutory distinctions, ASI helps preserve choice and allows credit unions to compete and serve their members without unnecessary regulatory barriers.
Building a Stronger
State Charter System
A strong state charter system gives credit unions the flexibility to grow, innovate, and better serve their members. ASI works with state regulators, lawmakers, leagues, and credit unions to modernize state laws, expand private deposit insurance opportunities, and preserve a competitive, free-market alternative to federal insurance. By strengthening state charters, we help create a more diverse and resilient credit union system.
Credit Union
Advocacy & Partnership
ASI is more than a share insurer—we are a trusted advocacy partner. We work alongside state leagues, credit unions, regulators, and industry stakeholders to advance sound public policy, address emerging legislative and regulatory issues, and strengthen the credit union movement. Together, we help ensure state-chartered credit unions have a strong voice at both the state and federal levels.
The Case for ASI Private Deposit Insurance
Proven Protection
with more than 50 years of experience.
Zero Member Losses
since 1974.
Financial Strength
backed by a higher reserve ratio than the federal program.
Flexibility for Specialized Lending
that helps credit unions meet unique member needs.
State Charter Advocacy
that strengthens local oversight and decision-making.
Regulatory Partnership
built on collaboration and responsiveness.
Cooperative Values
focused exclusively on credit unions and their missions.
Free-Market Insurance Model
providing an alternative to a federal mandate.
Innovation
developing products that fit a particular need rather than a one-size-fits-all model.
Equal Lending Access
that provides all individuals and groups with non-discriminatory opportunities to obtain credit
Private Deposit Insurance FAQs
Q. What are the differences between primary deposit insurance through the NCUA vs. ASI?
ASI’s coverage is more comprehensive than what is provided by the federal government. ASI’s protection is per account, not per member, meaning much more of your members’ deposits can be insured. Rather than a “one-size-fits-all” approach, we work with our member credit unions and state regulators to develop flexible programs that focus on meeting consumer needs and sustaining charters. Unlike the NCUA, at the heart of our business model is our belief in the right of credit unions to meet the needs of their members without undue outside interference in day-to-day operations. Also, ASI’s equity ratio — the ultimate measurement of our financial position — is well above that of our counterpart in the federal government.
Many of our partners prefer private insurance over federal regulation because it allows flexibility to develop solutions to meet the needs of their members and offers more protection by insuring up to $250,000 for each and every account, compared to the federal insured cap at $250,000 per member.
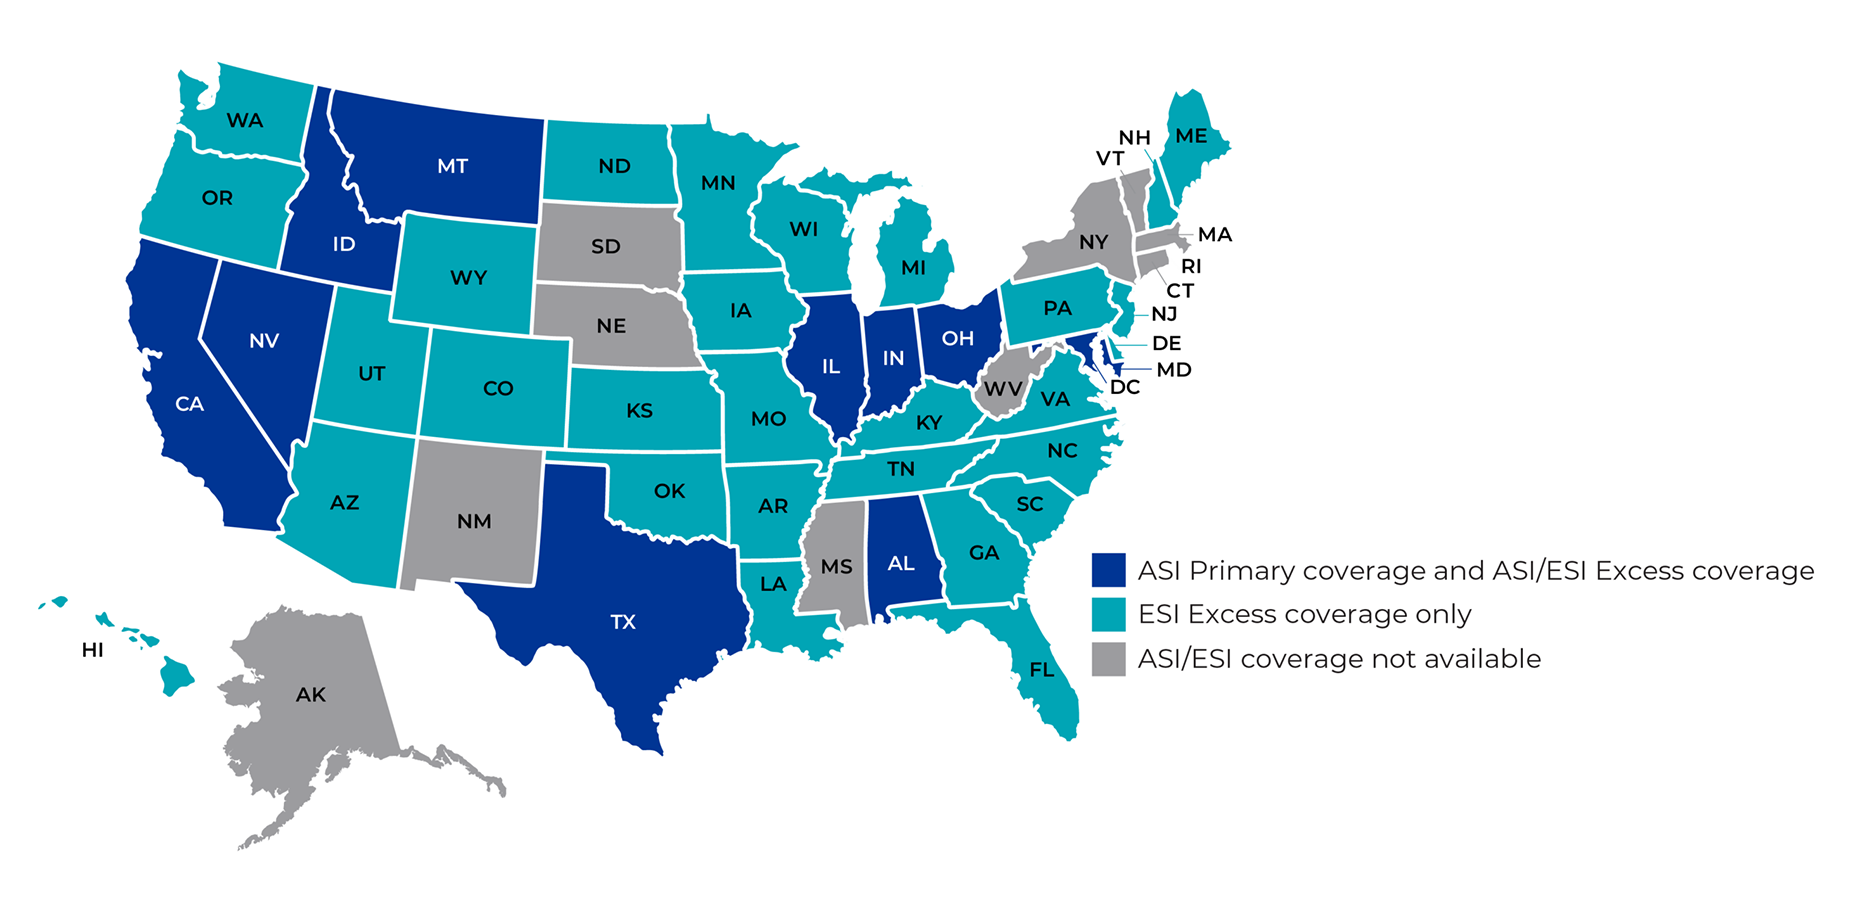
Also, ASI primary insured credit unions have the option of adding one of our excess insurance programs very quickly through our subsidiary ESI. By adding an excess insurance program on top of your current primary insurance, you can more easily stand out in your marketplace, which can be a strong differentiator in times like these. Through ESI credit unions may add up to $10,000,000 of additional deposit insurance to primary coverage limits on select classes of accounts such as Business Savings and Public Funds (Not available in the state of Washington).
Q. How many financial institutions use private insurance through ASI?
ASI currently insures the deposits of nearly 100 credit unions, and 1.35 million members in ten states, with total insured shares of almost $20 billion.
Q. How long has ASI been in business?
ASI has been protecting credit unions and their members since 1974, and no member has ever lost money in an ASI-insured credit union.
Q. Is ASI regulated or audited?
ASI is licensed by the Ohio Department of Insurance and dual-regulated by the Ohio Departments of Insurance and Commerce. Annually, a “big four” accounting firm audits the ASI’s financial statements, and an independent actuary attests to the sufficiency of ASI’s loss reserves.
Q. How does ASI mitigate against potential risks/losses?
The profile of our member credit unions, where they typically hold around 95% retail deposits, greatly lessens the risk of a depository “run.” Compare this to the situation at Silicon Valley Bank, for example, where the vast majority of deposits were uninsured commercial accounts.
Because of ASI’s risk management and workout programs, our loss ratio (losses compared to at-risk assets) is less than 3.0% — meaning our practices have been highly successful when “saving” or finding a good home for troubled members.
ASI’s investment duration is relatively short, and our practice is to keep a significant amount of cash on hand. We also have access to liquidity from several large financial institutions, including the Federal Home Loan Bank.
ASI’s primary deposit insurance is backed by reserves set aside, the assets of the organization, available lines of credit from three separate financial institutions, and the organization’s capital. Additionally, the backing of the entirety of ASI’s member credit unions would provide additional funding, should it be necessary.
Q. Can any credit union obtain coverage through ASI?
State chartered credit unions have the option of converting from federal to private deposit insurance through ASI. However, not every credit union that applies for ASI membership is approved. We carefully underwrite each applicant credit union that wishes to convert from federal deposit insurance to private deposit insurance. We utilize an extensive underwriting program that includes analysis of the applicant credit union’s financial position and financial trends over the past several years. We understand that the quality of a credit union’s financial statements cannot be based solely on a point-in-time assessment but must incorporate a review and understanding of trends — not just to see where a credit union has been recently, but to determine the likely forward-looking assessment of the institution’s condition. We also review operating policies and strategic plans and budgets to assess management’s plans and projections, as well as the governing controls established by the applicant credit union’s Board of Directors. Each primary applicant is also subject to a thorough on-site examination, including a review of accounting records, sampled loan files, and verification of cash and investment accounts.
Take Action.
Support the CUChoice Campaign
Credit unions deserve the opportunity to evaluate all viable deposit insurance options. American Share Insurance is working with credit union leaders, regulators, and policymakers to preserve private deposit insurance as a free-market alternative and strengthen the state-chartered credit union model.
Learn how private deposit insurance works, why it matters, and how your credit union can help support greater choice for the future of the credit union movement.
CUChoice, an initiative sponsored by American Share Insurance (ASI)
We’re focused on expanding the availability of private deposit insurance as an option for broader deposit insurance reform. The effort encourages growth and ensures individual states allow credit unions to choose the structure that best supports their mission and membership.
Yes, I Want More Information on ASI Advocacy Efforts
Add Your Voice for ChoiceNews & Resources
News & Updates
ASI in the News
Private Share insurance strengthens dual chartering: ASI-insured credit unions deliver competitive growth and strong capital.